Eligible buyers purchasing select Craft Homes built through the Oklahoma Homebuilder Program may receive a grant equal to 5% of the purchase price. The builder financing and buyer benefit are separate: Craft Homes received a 0% construction loan for eight homes, while the 5% grant is available only to eligible buyers purchasing select program homes with qualifying mortgage financing.
Important: An applicable program home must be occupied by its purchaser as a primary residence for at least three years, whether or not the buyer accepts the 5% down payment assistance.
Updated August 13, 2026: This article has been updated to reflect additional guidance from the Oklahoma Housing Finance Agency regarding the three-year primary-residence requirement, deed restrictions, DPA repayment, resale requirements, and buyer eligibility.
There is another important possibility. OHFA’s current product guide says the Housing Stability grant can be paired with its regular 3.5% down payment assistance program when the buyer qualifies and the lender follows OHFA’s Enhanced DPA guidelines. That can substantially reduce the buyer’s upfront cost, but the two percentages are calculated differently and the combined result should not be advertised as exactly 8.5% of the purchase price.
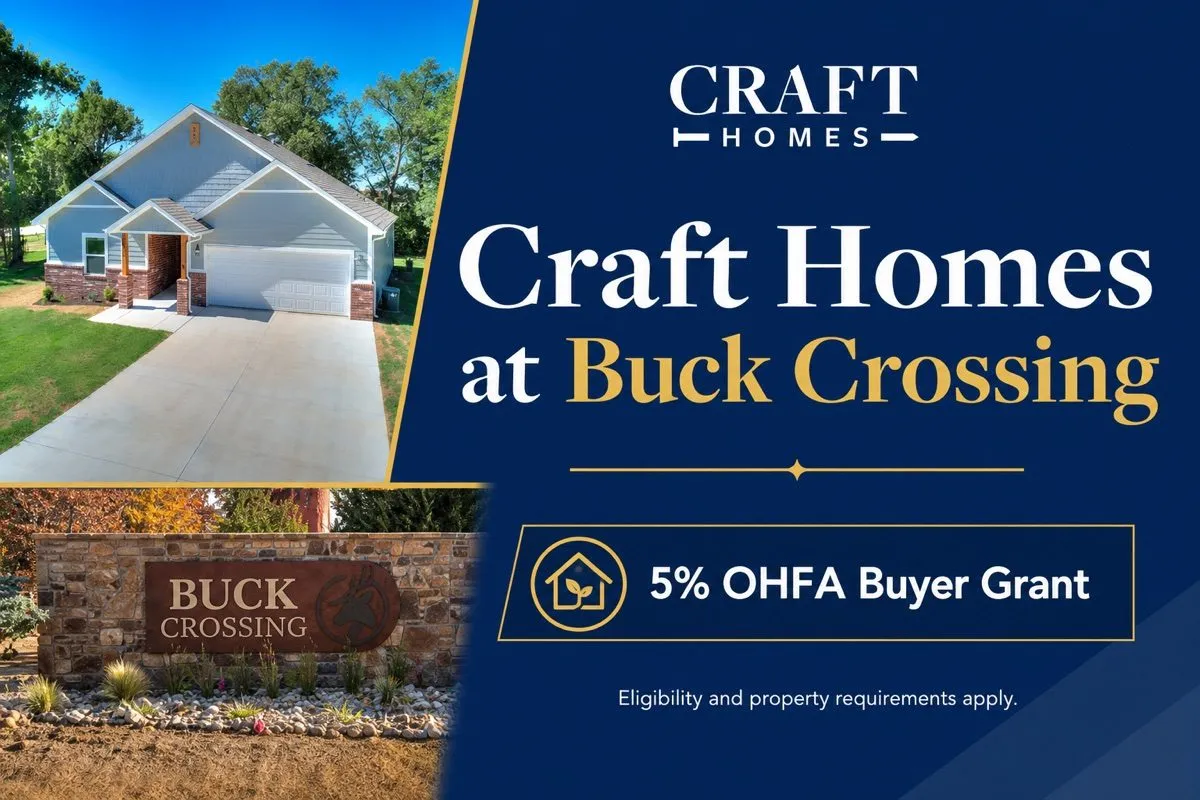
What OHFA approved for Craft Homes in Buck Crossing
In January 2026, OHFA approved Housing Stability construction financing for eight new Craft Homes in Buck Crossing on Stella Trail in Guthrie. The official award record identifies five 3-bedroom homes and three 4-bedroom homes.
This is where the wording matters. The Housing Stability Program provides the builder with a 0% interest construction loan. It does not give the builder a 5% construction loan. The 5% benefit belongs on the buyer side of the transaction and applies only when a buyer purchases an eligible home built with OHFA-administered funds.
Craft Homes currently markets more than eight available homes in Buck Crossing. That means buyers should not assume every home in the community qualifies. OKC Metro Group represents several Craft homes there, and we can help identify the current properties connected to this award. The buyer’s lender and OHFA must verify final property and borrower eligibility.
What the buyer may receive
OHFA’s February 2026 Housing Stability product guide sets the assistance at 5% of the purchase price. On a $272,500 home, for example, 5% would equal $13,625. That is simple arithmetic for illustration, not a loan quote or approval.
The assistance can be applied in this order:
- The minimum down payment required by the first mortgage
- Normal and customary closing costs
- A reduction of the first-mortgage principal
OHFA also permits reimbursement of certain costs the buyer may have already paid, including earnest money, the credit-report fee, and the appraisal fee. Any remaining assistance is applied to principal reduction. The funds are not paid to the buyer as unrestricted cash, and they cannot be used to buy down the mortgage interest rate.
The benefit is not limited to one mortgage type
One of the most useful features is flexibility. The current guide says the 5% Housing Stability grant may be used with the buyer’s choice of government or conventional first mortgage through an approved lender. Depending on the home and borrower, that could include an FHA, VA, USDA, or conventional path. The lender and first-mortgage investor determine the required credit score, payment and total debt ratios, reserves, automated-underwriting findings, and final loan approval.
There are no income restrictions for the 5% Oklahoma Homebuilder Program DPA. That does not mean every buyer automatically qualifies. Buyers must still qualify for their first mortgage and satisfy all applicable lender, investor, property, and program requirements. The home must be an eligible OHFA-funded property, remain within the applicable purchase-price limit, and meet the program’s occupancy and deed-restriction requirements.
Cash buyers are not eligible to receive the 5% DPA. The purchase must be financed with a mortgage loan. A cash buyer purchasing an applicable program home may still be subject to the program’s three-year primary-residence and deed-restriction requirements. DPA eligibility and the underlying property restriction are separate questions.
As of August 13, 2026, OHFA lists Oklahoma Homebuilder Program purchase-price limits of $338,419 for a 3-bedroom home and $371,477 for a home with four or more bedrooms. Those limits mirror HUD Section 234 requirements and can change, so the current figure must be checked again before a buyer relies on it.
The 3-Year Occupancy Requirement, Deed Restriction And Grant Forgiveness
Applicable Oklahoma Homebuilder Program homes must be occupied by the purchaser as their primary residence for at least three years. This requirement belongs to the program home itself and is not created only when a buyer accepts the 5% DPA.
A deed restriction is recorded at closing to enforce the three-year primary-residence requirement. A purchaser who declines the 5% DPA must still sign a deed restriction requiring the property to remain their primary residence for three years. Because that buyer did not receive a grant, this version of the restriction does not contain DPA repayment provisions.
For a buyer who accepts the 5% DPA, the DPA itself carries 0% interest, no monthly payment, and no added OHFA fee. Separate lender origination or administrative fees may apply. The grant becomes fully earned after 36 months of qualifying primary-residence occupancy. OHFA’s published program guide supports the 1/36 calculation: for each qualifying month, 1/36 of the original assistance is earned.
If a homeowner who received DPA leaves the property as a primary residence or sells it before completing the three-year occupancy period, the homeowner must repay the prorated unearned portion of the grant to OHFA. A job transfer, military move, or other relocation does not make that obligation disappear, so buyers should understand it before closing.
There is also a separate resale-price rule. If the property is sold during the three-year restriction period, the sales price must comply with the applicable HUD Section 234 purchase-price limit in effect at the time of sale. That limit should be verified as part of any early-sale plan rather than assumed from the amount in effect when the home was originally purchased.
After the required three-year occupancy period is completed, the DPA is fully earned or forgiven according to the applicable program rules. The buyer’s lender, closing professionals, and OHFA should confirm the exact recorded documents and release process for the specific transaction.
Can a parent’s gift be added to the 5% OHFA grant?
Potentially, yes. OHFA’s 2026 Housing Stability notice recognizes additional gift funds from allowable sources, but the first-mortgage program and lender decide whether a parent’s gift is acceptable and what documentation is required. For example, Fannie Mae’s published conventional guidance allows gifts from qualifying relatives for down payment and closing costs. FHA, VA, and USDA loans follow their own rules.
Do not move the money casually. Before the parent sends anything, the lender should confirm the donor is eligible, identify the required gift letter, and document the transfer trail. The lender must also calculate how the 5% OHFA funds, the parent’s gift, seller-paid costs, and any legacy 3.5% OHFA assistance interact so the transaction does not exceed program or first-mortgage limits. Review the 2026 OHFA Housing Stability notice and Fannie Mae’s gift-fund guidance, then obtain the approved lender’s written answer for the specific loan.
Can a buyer add OHFA’s regular 3.5% assistance?
Potentially, yes. OHFA’s current Housing Stability guide expressly addresses coupling the 5% grant with its legacy 3.5% DPA program. The lender must follow the Enhanced DPA guidelines, and the buyer must qualify for the selected legacy product.
The distinction is important:
- The Housing Stability grant equals 5% of the purchase price.
- OHFA’s Legacy assistance equals 3.5% of the applicable loan amount.
- The regular OHFA product has its own income, purchase-price, loan-type, and underwriting requirements.
- The Housing Stability grant cannot be added to an OHFA Dream Zero loan.
The right comparison is not simply “5% versus 8.5%.” Ask the lender to prepare side-by-side estimates using the same home, closing date, taxes, insurance, and borrower information. Compare the cash needed at closing, monthly payment, interest rate, APR, total assistance, recorded liens or restrictions, and long-term cost.
What makes Buck Crossing worth a closer look
Buck Crossing is a Craft Homes community in south Guthrie with access to I-35 and wooded homesites that generally begin around one-half acre. Craft’s official community page showed 9 available homes and prices starting at $257,500 when checked August 13, 2026. Prices, construction status, incentives, and availability can change quickly.
The Housing Stability benefit makes the select OHFA-funded homes especially worth comparing, but financing should never be the only reason to choose a property. Buyers should also evaluate the floor plan, lot, estimated completion, inspections, warranty, commute, taxes, insurance, neighborhood restrictions, and likely length of ownership.
For more background, read our guide to Craft Homes new construction in Guthrie, our OKC metro new-construction resource, and the explanation of OHFA repayment rules.
Confirm the home and financing before you rely on the benefit
Doug Arnett and Ronnie Jordan at OKC Metro Group can show you the Craft Homes inventory we represent in Buck Crossing and help confirm which addresses are tied to the OHFA award. Brett Baldwin with Revolution Mortgage can help compare available first-mortgage choices and verify the current financing requirements.
Rates, eligibility, assistance, and loan approval are never guaranteed. The lender and OHFA must verify final eligibility. Official OHFA documents, lender documents, title documents, and the recorded deed restriction control over this general blog explanation. Ask Brett for a written comparison and confirmation from the appropriate OHFA-approved lending channel before relying on the program in an offer. We’re building futures through real estate, and this is exactly the kind of opportunity that deserves both excitement and careful verification.